The distinction between utility and security tokens is key for crypto projects, as misclassification can lead to fines, shutdowns, or legal disputes. In 2026, clearer regulatory frameworks are making token classification easier to navigate.
The U.S. has introduced clearer guidance through the Securities and Exchange Commission (SEC)’s Project Crypto initiative, while Europe’s MiCA framework has been fully operational since late 2024.
Singapore, Dubai, and Japan also have established regulatory approaches. Understanding these rules helps issuers determine which requirements apply, what documentation is needed, and how tokens can be legally offered.
This guide explains utility and security tokens in simple terms, explores how regulators distinguish between them, reviews important court decisions, and provides a practical framework for determining which category a token belongs to.
Principais lições
The label doesn’t matter; the substance does. Calling a token “utility” doesn’t protect it from being a security if it walks and talks like an investment.
Timing matters a lot. Selling a token before your product actually works is one of the biggest red flags regulators look for.
Decentralization can change a token’s status over time, but it does not erase liability for how it was sold in the first place.
Security tokens aren’t something to be afraid of. If your token is genuinely an investment, like a share in a real estate deal, it’s meant to be a security. Structure it that way from day one.
2026 brought real regulatory clarity. The SEC’s Project Crypto, MiCA in the EU, and frameworks in Dubai and Singapore all give founders and investors a clearer map than existed even two years ago.
Junte-se à UEEx
Experimente a plataforma líder mundial em gestão de patrimônio digital
A utility token is a digital asset that gives you access to something: a service, a feature, or a product inside a specific blockchain platform. Think of it less like a stock and more like an arcade token. You buy it so you can use it, not so you can sit on it and wait for it to grow.
What makes a token a utility token:
It’s for using, not investing. You spend it to pay for something, like a transaction fee or storage space.
It’s not sold as an investment. No promises of price growth, no “get in early” pitches.
Its value comes from use, not from a company’s performance.
It often gets consumed. Ethereum’s ETH, for example, is spent to pay for network transactions.
It usually only matters within its own ecosystem.
Exemplos comuns:
ETH pays for transaction fees (“gas”) on the Ethereum network.
FIL pays for decentralized data storage on Filecoin or is earned by providing storage.
BAT rewards Brave browser users for viewing privacy-respecting ads and lets them tip creators.
Here’s the catch: just calling your token a “utility token” doesn’t make it one in the eyes of the law. The SEC has made clear it does not view labels as the deciding factor. What matters is how the token is actually sold and what buyers reasonably expect from it.
A token de segurança represents ownership or a financial stake in something real: a company, a piece of real estate, a debt, or a share of future profits. It’s the blockchain version of a stock certificate or a bond.
What makes a token a security token:
It represents ownership or a claim on value, like equity, debt, or property.
Buyers expect a financial return, whether through price growth, dividends, or profit sharing.
Its value is tied to an underlying asset or a company’s performance, not to using a product.
It’s regulated; security tokens fall under securities law, which means registration or a valid exemption, disclosure requirements, and ongoing reporting.
Tipos comuns:
Tokens de capital representing shares in a company
Tokens de dívida representing loans or bonds
Real estate tokens representing fractional ownership of property
Revenue-share tokens that pay holders a cut of a project’s income
A useful, if imperfect, real-world comparison: a real estate token that pays daily rental income to holders works a lot like owning a small slice of a rental property through an LLC. That’s exactly the structure platforms like RealT use in the US, and it’s why those tokens are treated as securities, not utility tokens.
The Howey Test: How Regulators Decide Utility vs Security Tokens
This is the single most important legal tool in this entire topic, so it deserves its own section.
The Howey Test comes from a 1946 Supreme Court case, SEC v. WJ Howey Co., which had nothing to do with crypto. It involved orange groves in Florida. Investors bought land and leased it back to the company, which tended the groves and split the profits. The Supreme Court had to decide: Is this arrangement a security?
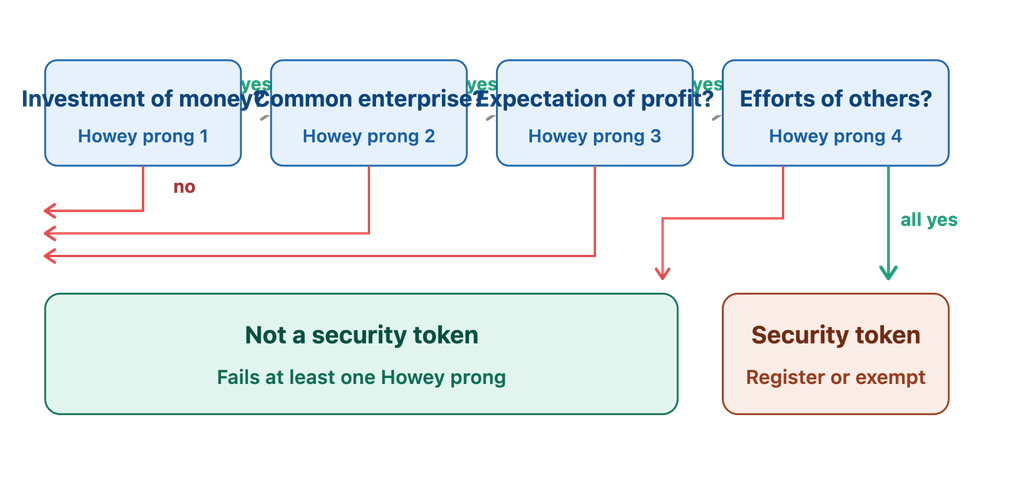
The Court said yes, and in doing so it created a four-part test. A deal is an “investment contract” (a type of security) if it involves:
Um investimento de dinheiro (or crypto, or anything of value)
Em uma empresa comum
Com expectativa de lucro
That comes mainly from the efforts of someone else
If a token deal checks all four boxes, it’s a security. If it clearly fails on even one, it’s probably not.
“If the network on which the token or coin is to function is sufficiently decentralized … the assets may not represent an investment contract,” former SEC Division of Corporation Finance Director William Hinman said when discussing Ether back in 2018, a comment that still shapes how regulators think about decentralization today.
Applying the four parts to tokens:
1. Investment of money: Almost every token sale satisfies this. Paying with dollars, Bitcoin, or even providing services all counts.
2. Common enterprise: Are buyers’ fortunes tied to each other or to the project’s success? This part has actually been controversial. The SEC has argued in past guidance that it doesn’t strictly require pooled funds to find a common enterprise, a stance that stretches the plain language of the original Howey ruling and remains a point of legal debate.
3. Expectation of profit: This is where marketing really matters. If your pitch talks about future value, comparisons to stocks, or a roadmap that will increase token value, you’re pointing straight at a security.
4. Efforts of others: If buyers are passive and success depends entirely on your core team building the product, that leans toward security. If the network runs itself with no single controlling party, that leans away from it.
Uma maneira simples de lembrar:
Bitcoin fails the test almost immediately since there’s no company, no promoter, and no one whose efforts make it work. That’s why regulators have long treated Bitcoin as a commodity rather than a security.
A brand-new token sold before the platform exists, with a website promising the team will “build value,” checks every box. Most real tokens live somewhere in between, which is why the details of the sale matter so much.
Utility Tokens vs Security Tokens: Side-by-Side Comparison
Recurso / Aspecto
Tokens de utilidade
Tokens de segurança
Objetivo Primário
Provide access to products, services, features, or functions within a blockchain ecosystem
Represent an investment or financial interest, such as equity, debt, fund interests, or other securities
Derivação de valor
Primarily linked to network use, utility, supply and demand
Generally linked to an underlying security, asset, business, or financial return
Status Regulatório
May fall outside securities laws when structured and offered as a genuine utility/non-security crypto asset
Subject to securities laws when the token itself represents a security or is offered as part of a securities transaction
Teste de Howey
Utility does not automatically exempt a token; the specific transaction and circumstances matter
Investment contracts generally involve an investment of money, a common enterprise, and an expectation of profits from others’ efforts
Security Token Offerings (STOs), registered offerings, or securities exemptions such as private placements
Typical Investor/User
Users, customers, network participants, and traders
Investors seeking economic, ownership, or other financial rights
Direitos Concedidos
Platform access, usage rights, discounts, governance or network functions
Equity, income, dividends, voting rights, debt claims, fund interests, or other contractual rights
Registro da SEC
Not necessarily required if the asset and transaction are outside federal securities laws
Generally required unless the offering qualifies for an exemption
KYC / AML
Depends on the platform, jurisdiction, and use case
Typically more extensive due to securities, AML, and investor-verification requirements
May trade on crypto exchanges where legally permitted
Trading may require regulated securities venues, broker-dealers, ATSs, or other authorized infrastructure
Transferibilidade
Often designed to be transferable, subject to applicable laws and platform rules
Frequently subject to securities-law, contractual, or holding-period restrictions
Profit Expectations
A genuine utility model emphasizes use rather than returns generated by a promoter’s efforts
Investment returns are generally central to the investment thesis
Garantia de Ativos
Usually not backed by an underlying financial asset
Can represent or be backed by equity, debt, funds, real estate, or other securities
Exemplos
ETH as a network utility, digital tools, and certain non-security crypto assets
Tokenized shares, tokenized bonds, fund interests, and other tokenized securities
Complexidade regulatória
Low to high depending on jurisdiction, structure, and offering
Generally high because securities regulations apply
Custos Legais e de Conformidade
Can be lower, but depend heavily on jurisdiction and structure
Usually higher because of registration, disclosure, investor eligibility, custody, and trading requirements
Time to Market
Potentially faster when no securities registration or equivalent authorization is required
Usually slower because of securities-law and compliance requirements
Conformidade contínua
May be limited, although consumer-protection, AML, tax, and other rules can still apply
Typically includes ongoing reporting, disclosure, recordkeeping, transfer, and regulatory obligations
2026 U.S. Regulatory Position
The SEC’s 2026 framework recognizes categories such as digital tools and other non-security crypto assets; however, a non-security asset can still be involved in an investment contract
The SEC identifies digital securities as tokenized financial instruments that fall within the securities definition; tokenization does not remove securities-law obligations
Atualização importante de 2026
The biggest change from older crypto-token comparisons is that “utility token = unregulated” is too simplistic. In March 2026, the SEC issued an interpretation creating a clearer taxonomy for crypto assets, including digital commodities, digital collectibles, digital tools, stablecoins, and digital securities.
It also clarified that a non-security crypto asset can nevertheless be part of an investment contract depending on how it is offered and the promises made to purchasers.
For tokenized securities, the SEC’s 2026 guidance makes the distinction particularly clear: putting a traditional security on a blockchain does not change its underlying legal character
Real-World Examples That Make This Click
Here are some real-world examples for easier understanding
Utility Tokens in Practice
Símbolo de atenção básica (BAT)
BAT powers the Brave browser’s advertising model. Users who opt in earn BAT for viewing privacy-respecting ads, and they can spend that BAT tipping content creators or unlocking features.
Nobody buys BAT expecting Brave’s team to “make it go up.” They use it because it does something. That functional, spend-it-to-use-it design is exactly why BAT has avoided being treated as a security.
Filecoin (FIL)
FIL works the same way for data storage. Need storage space? Pay in FIL. Have spare hard drive space? Earn FIL by renting it out. The token is the currency of an actual marketplace, not a passive investment vehicle.
Ethereum (ETH)
This utility token is the classic transitional case. Ethereum raised money through a 2014 token sale, which looked a lot like a securities offering at the time. But over a decade, the network became genuinely decentralized: thousands of independent developers, validators, and node operators, with no single company calling the shots.
Today, ETH is needed to pay for every transaction and smart contract on the network. Regulators have not pursued Ethereum as a security, largely because of that shift from team-driven to community-run.
This token lets investors buy fractional shares of US rental properties. Each property sits in its own LLC, and token holders get a slice of the rental income, distributed regularly. That’s not a utility; it’s ownership with an income stream, which is why RealT structures its offerings under securities exemptions and restricts sales to qualifying investors.
Tokenized real estate in the Gulf region
This project has also taken off. Dubai’s Virtual Assets Regulatory Authority created a specific category for tokenized real-world assets, and property tokenization projects there have drawn strong international investor interest, another sign that regulated security token markets are maturing quickly outside the US.
Japan’s tokenized REITs
The initiative shows how far this can go in a well-regulated market. Japan’s Financial Services Agency has allowed tokenized real estate investment trusts to trade under existing securities rules, and tokenized offerings have become a meaningful share of new listings on the Tokyo Stock Exchange in recent years.
The Regulatory Picture in 2026
This is how the regulatory picture is playing out in 2026
United States: The SEC’s Project Crypto
For years, the SEC criptografia regulamentada mostly through lawsuits rather than clear rules. That changed in 2025.
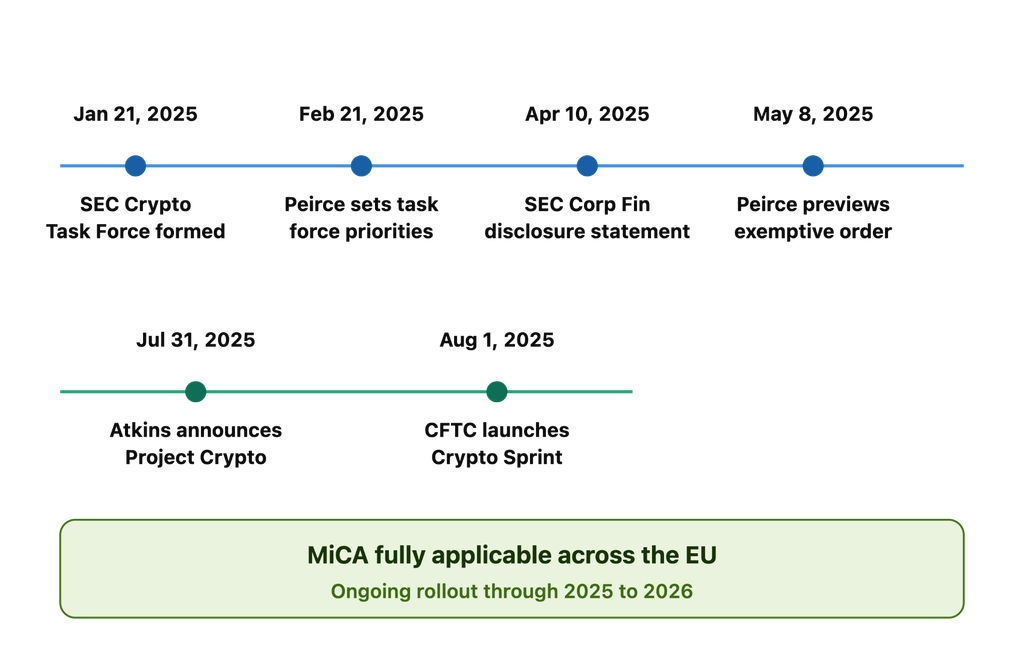
On July 31, 2025, SEC Chairman Paul Atkins announced Criptografia do Projeto, a commission-wide plan to modernize how the SEC treats digital assets. In that speech, Atkins argued that most cryptocurrencies are not securities at all and that classification should depend on how a token is packaged and sold, not on some inherent quality of the technology.
“A commission-wide initiative to modernize the securities rules and regulations to enable America’s financial markets to move on-chain” is how Atkins described Project Crypto in his announcement.
Project Crypto is pushing toward:
Clearer guidelines for telling securities, commodities, and stablecoins apart
New exemptions and safe harbors built specifically for token sales, including possible relief for early-stage projects that haven’t launched yet
A path for security tokens to trade on distributed ledger technology with lighter registration requirements, an idea Commissioner Hester Peirce has championed
Room for DeFi to keep operating, distinguishing genuine software publishers from regulated intermediaries
The shift in approach showed up fast in the SEC’s actual casework. In February 2025, the agency dropped its lawsuit against Coinbase over unregistered securities trading.
Also, by mid-2025, the SEC and Ripple Labs ended their years-long legal fight over XRP: Ripple paid a $125 million penalty tied to its institutional sales, both sides dropped their appeals, and the earlier court finding that XRP is not a security when trading on the open market stood as the final word.
European Union: MiCA
While the US has leaned on court-by-court analysis, the EU built an actual rulebook. The Regulamentação de Mercados de Criptoativos (MiCA) became fully applicable across all 27 member states in December 2024, and it sorts tokens into clear buckets instead of relying on a decades-old test.
MiCA’s three main categories:
E-money tokens (EMTs): pegged to a single currency, like USD-backed stablecoins
Asset-referenced tokens (ARTs): backed by a basket of assets, such as multiple currencies or commodities
Other crypto-assets, including utility tokens: tokens meant purely to provide access to a good or service from the issuer, not to hold stable value or serve as an investment
Under MiCA, a genuine utility token needs a clear whitepaper and honest marketing, but it avoids the heavier licensing rules that apply to stablecoins and investment-like tokens. That gives EU-based projects a much more predictable path than the US case-by-case approach.
Asia-Pacific: Singapore, Dubai, and Japan
Cingapura Monetary Authority (MAS) treats tokens with ownership or profit-sharing features as securities under its existing Securities and Futures Act, with licensed platforms handling compliant offerings.
Dubai's Virtual Assets Regulatory Authority (VARA) built a category specifically for tokenized real-world assets, supporting a wave of real estate tokenization projects.
Japão Financial Services Agency has allowed tokenized REITs to operate under its securities framework, making Japan one of the more mature markets for regulated security tokens.
MiCA vs. SEC Approach: Key Differences
The EU’s MiCA provides a harmonized framework with defined categories and requirements, while the U.S. SEC’s 2026 approach uses a more detailed token taxonomy alongside existing securities-law principles. The SEC issued a major crypto-assets interpretation in March 2026, replacing its earlier 2019 digital-asset framework.
Aspecto
MiCA (EU)
SEC Approach (U.S.)
Quadro
A broad, category-based framework covering crypto-assets, ARTs, EMTs, and service providers.
2026 SEC interpretation establishes categories including digital commodities, digital collectibles, digital tools, stablecoins, and digital securities.
Clareza regulatória
Relatively high, with defined rules for different crypto-asset categories and regulated activities.
Greater clarity than under the previous framework, but securities status can still depend on the asset, transaction, and surrounding circumstances.
Tokens de utilidade
Covers crypto-assets that are not financial instruments, with specific requirements for issuance and disclosure.
“Digital tools” that perform practical functions are generally not securities, provided they do not involve an investment contract.
Stablecoins
Separates stablecoins into Asset-Referenced Tokens (ARTs) and E-Money Tokens (EMTs), with specific requirements for issuers and reserves.
Payment stablecoins meeting specified conditions are generally not securities; other stablecoins may receive different treatment depending on their characteristics.
Autorização
Crypto-asset service providers generally require authorization under MiCA, subject to applicable exemptions and transitional arrangements.
Securities-related crypto activities may require registration or qualify for an applicable exemption under federal securities laws.
Consumer/Investor Focus
Emphasizes consumer protection, market integrity, disclosure, and prudential requirements.
Primarily focuses on investor protection under securities laws, while the 2026 framework also seeks clearer regulatory boundaries for crypto markets.
What the Major Court Cases Actually Decided
Court rulings shape this area of law as much as any regulation. Here’s what actually happened in the cases that matter most, verified as of September 2026.
The DAO Report (2017)
This is where it all started for crypto. The SEC investigated “The DAO,” an early Ethereum-based investment fund, and concluded its tokens were securities because investors handed over money expecting returns generated by the fund’s organizers. It set the template every later case has built on.
SEC v. Telegram (2020)
Telegram raised $1.7 billion selling “Gram” tokens before its network ever launched. A court blocked the distribution, ruling that buyers were investing based on Telegram’s promise to build a working blockchain, not on any existing utility.
A lição: selling a token before your product works is one of the clearest paths to a securities violation, no matter what the token eventually does.
SEC v. LBRY (2022)
LBRY argued its LBC token was a utility token for its content platform. The court disagreed, pointing out that LBRY marketed LBC’s investment potential and that the token had little real functionality at the time it was sold. The label “utility token” did not save the company.
SEC vs. Ripple Labs
This case produced one of the most talked-about rulings in crypto law. In 2023, a federal judge found that Ripple’s direct sales of XRP to institutional investors were securities transactions.
However, its sales through public exchanges to retail buyers were not, since exchange buyers had no way of knowing they were buying from Ripple. By 2025, Ripple agreed to pay a $125 million penalty over the institutional sales, both sides dropped their appeals, and the case closed with that split ruling standing.
SEC x Coinbase
Filed in 2023, this case accused Coinbase of running an unregistered securities exchange. Under the new SEC leadership, the agency voluntarily dismissed the case in February 2025, citing its broader shift toward building clear rules instead of litigating case by case.
How to Tell If Your Token Is Utility or Security
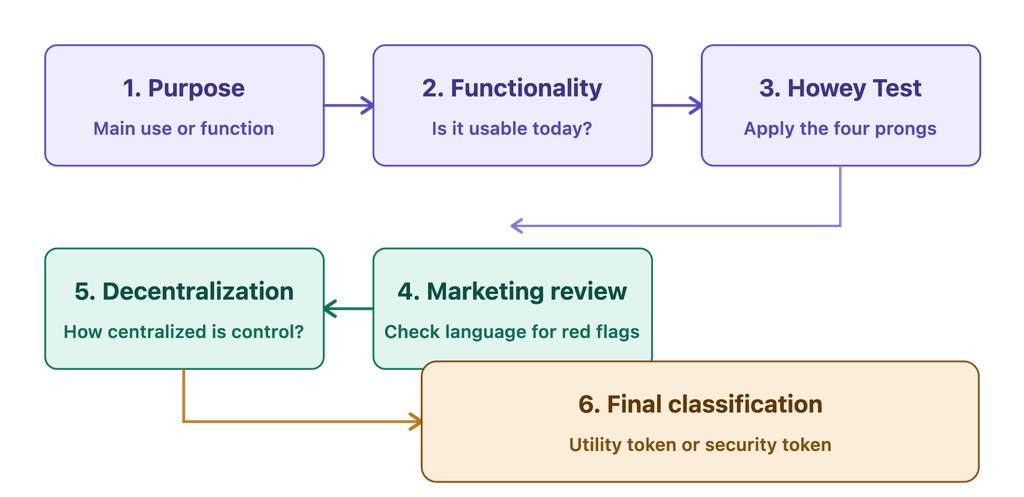
Walk through these questions in order.
1. What does the token actually do? If it unlocks a feature, pays for a service, or gets consumed during use, that points toward utility. If it represents ownership, a share of profits, or a claim on an asset, that points toward security.
2. Would the token have value even if nobody expected to profit from it? A utility token should be worth something just because people want to use the platform. If its entire value depends on the price going up, that’s an investment, not a utility.
3. Run it through the Howey Test. Did people pay money? Did they expect profit? Does that profit depend mainly on your team’s work rather than their own use of the product? If you’re answering “yes” across the board, you’re likely looking at a security.
4. When are you selling it? Selling before your platform works is the single biggest red flag regulators look for. SEC x Telegrama exists because of this exact issue. If the token is already functional at the moment of sale, your utility argument is much stronger.
5. How decentralized is the network, really? Ask who controls development, who makes governance decisions, and whether the network could keep running if your company disappeared tomorrow. More independence from a central team weakens the “efforts of others” argument that makes a token a security.
6. Read your own marketing back to yourself. Words like “investment opportunity,” “expected returns,” or “get in before the price rises” are red flags. Language about “using the platform” or “accessing features” supports a utility argument. Have a lawyer review every public-facing document before launch, not after.
If your token checks the security boxes, that’s not a failure. It just means you need to structure the offering properly, using an exemption like Regulamento D or Regulamento A + in the US, or the appropriate MiCA or MAS pathway if you’re launching in the EU or Singapore.
Common Misconceptions About Crypto Token Regulation
Here are common mistakes about crypto token regulation that you should know
1. Calling it a utility token means it isn’t a security
Realidade: The label alone does not determine the legal treatment. Regulators and courts look at the asset’s characteristics, transaction structure, and economic substance. The SEC’s 2026 interpretation distinguishes between the crypto asset itself and an investment contract involving that asset. The LBRY case also shows that calling a token a “utility token” does not automatically protect an issuer from securities laws.
2. Utility means a token cannot be a security
Realidade: A token can have genuine utility while a particular sale or arrangement qualifies as an investment contract. The key issue is whether buyers reasonably expect profits from the essential managerial efforts of others. Functionality, marketing, promises, and the surrounding transaction all matter.
3. If Bitcoin isn’t a security, every crypto asset is safe
Realidade: Crypto assets require individual analysis. Under the SEC’s 2026 interpretation, Bitcoin and Ether, along with several other named assets, are examples of digital commodities rather than securities. However, a transaction involving a non-security crypto asset can still constitute an investment contract depending on its structure.
4. Decentralization eliminates all securities-law concerns
Realidade: Decentralization can affect an asset’s classification, but it does not automatically erase the legal consequences of earlier transactions. The SEC’s 2026 framework specifically recognizes that a non-security crypto asset can be connected to an investment contract and that this relationship can later end.
5. Regulation D allows fundraising from anyone
Realidade: Rule 506(c) permits general solicitation but requires all purchasers to be accredited investors, with reasonable verification steps. Rule 506(b) allows up to 35 non-accredited investors who meet specific sophistication requirements, but generally prohibits general solicitation. Self-certification alone is insufficient for 506(c).
6. Selling overseas avoids U.S. securities laws
Realidade: Simply targeting foreign buyers does not automatically remove U.S. securities-law requirements. Regulation S provides a framework for qualifying offshore offerings, but issuers must satisfy conditions such as conducting an offshore transaction and avoiding directed selling efforts in the United States.
7. Airdrops are always exempt
Realidade: An airdrop’s treatment depends on its structure and circumstances. The SEC’s 2026 interpretation specifically addresses airdrops and recognizes that transactions involving otherwise non-security crypto assets can still implicate investment-contract analysis. The details of the distribution therefore matter.
Bottom line: Token regulation is no longer simply a question of whether an asset has “utility.” In 2026, issuers must examine the token’s characteristics and the specific transaction, promises, distribution method, and economic expectations surrounding it.
Fatores de risco e considerações
Token projects face different risks depending on whether they are structured as utility tokens or securities.
Risks for Utility Token Projects
1. Regulatory classification
Calling a token a “utility token” does not automatically determine its legal status. In the U.S., regulators and courts examine the token’s structure, sale, and surrounding transactions. The SEC’s 2026 interpretation now distinguishes between crypto assets and investment contracts, making the analysis more fact-specific.
Os principais riscos incluem:
Enforcement action or litigation
Registration or exemption requirements
Penalties and potential investor claims
Exchange restrictions or reduced liquidity
Mitigação: Obtain advice from experienced securities counsel, ensure genuine utility exists, avoid investment-return marketing, and maintain clear records of the token’s purpose and functionality.
2. Failure to deliver promised utility
If advertised functionality never materializes, projects may face allegations of misleading marketing or consumer-protection violations.
Melhores práticas: Launch only when core functionality is achievable, publish realistic roadmaps, provide regular development updates, and avoid overstating future capabilities.
3. Volatility and limited investor protection
Utility tokens can experience substantial price swings. Buyers may also have fewer protections than investors in registered securities, making voluntary transparency, risk disclosures, and strong governance particularly important.
4. Dependência de plataforma
A token’s value may depend heavily on the success of its underlying platform. Low adoption, centralized control, technical failures, or stronger competitors can undermine demand.
Risks for Security Token Projects
1. Higher compliance burden
Security-token issuers may face continuing obligations involving disclosures, recordkeeping, investor verification, transfer restrictions, and regulatory filings. Compliance costs can be significant and should be built into the business model from the outset.
2. Restricted liquidity and market access
Security tokens cannot necessarily trade freely on mainstream crypto exchanges. Depending on the exemption used, transfers may be restricted and secondary markets may be limited. For example, restricted securities can be subject to six-month or one-year holding periods under Rule 144.
3. Accredited-investor restrictions
Under Regulation D Rule 506(c), issuers can generally advertise an offering, but every purchaser must be an accredited investor, and the issuer must take reasonable steps to verify that status. This can significantly narrow the potential investor base.
4. Valuation challenges
Tokens representing real-world assets such as property can face difficulties around appraisals, price discovery, liquidity, and the relationship between the token price and underlying asset value. Independent valuations and transparent asset reporting can help reduce uncertainty.
5. Cross-border regulatory complexity
International offerings add another layer of compliance. In the EU, MiCA establishes a harmonized framework for many crypto-assets, covering areas such as disclosure, authorization, supervision, and investor protection. However, assets that qualify as financial instruments can fall outside MiCA and remain subject to existing securities rules.
Ultimately, both models involve trade-offs: utility tokens may offer greater flexibility but face classification and execution risks, while security tokens provide a more regulated framework but typically carry greater compliance, transfer, and market-access constraints.
Crypto regulation is moving toward clearer classifications, risk-based requirements, and more defined rules for tokenized securities. The EU’s MiCA already provides a harmonized framework, while the U.S. SEC introduced a crypto-asset interpretation in March 2026 that distinguishes digital securities from categories such as digital commodities and digital tools.
By 2027, major jurisdictions will likely become more compatible on core principles, although complete harmonization remains unlikely because regulatory approaches still differ.
More flexible U.S. rules
SEC Chairman Paul Atkins has proposed a potential token safe harbor that could give projects greater certainty about when crypto assets fall outside securities laws, subject to conditions. This could lower compliance barriers and encourage legitimate token issuance.
More guidance, less uncertainty
Regulators are increasingly providing formal interpretations and frameworks rather than relying solely on enforcement. However, fraud and non-compliant offerings will remain enforcement priorities.
Technology and Market Trends
RWA tokenization takes center stage
Real-world assets, including real estate, bonds, private equity, and commodities, are moving onto blockchain networks. Institutional-grade standards such as ERC-7943 are emerging, while regulatory developments are making compliant tokenization more practical.
By 2027, tokenized assets could become a more familiar investment option alongside traditional securities and REITs.
DeFi meets regulated finance
The next phase will likely combine DeFi efficiency with compliance controls such as KYC, transfer restrictions, and regulated custody. This hybrid approach could allow security tokens to access blockchain-based lending, trading, and settlement without abandoning investor protections.
Cross-chain interoperability improves
Financial institutions are working toward infrastructure that allows tokenized assets to move across different networks. Swift, for example, has tested blockchain interoperability with Chainlink and is now preparing live tokenized-payment pilots involving 17 banks.
A adoção institucional acelera
Banks and financial institutions are moving beyond experimentation toward practical blockchain infrastructure. This trend should expand tokenized securities into wealth management, payments, and capital markets.
AI strengthens compliance
AI will increasingly automate KYC, transaction monitoring, smart contracts, risk detection, and regulatory checks. Combined with blockchain’s transparency, this could reduce compliance costs while helping firms identify risks earlier.
Olhando para o futuro
The utility token vs security token question isn’t going away, but the rules for answering it are finally getting clearer. Project Crypto, MiCA, and frameworks in Singapore, Dubai, and Japan are converging on a similar idea: look at what a token actually does and how it’s actually sold, not what it’s called.
For anyone building, buying, or trading tokens in 2026, that clarity is good news. Projects that structure their offerings honestly, whether as a utility token or a properly registered security, are the ones that will still be standing in a few years. The ones trying to dress up an investment as a “utility” are the ones regulators are watching closely.
Junte-se à UEEx
Experimente a plataforma líder mundial em gestão de patrimônio digital
Can a token start as a security and later become a utility token?
Yes, this can happen through a process sometimes called progressive decentralization. If a network becomes genuinely community-run, with no single company or team essential to its operation, later transactions may fall outside securities law. However, this does not erase liability for how the token was originally sold. An early sale made before the network was functional can still count as an unregistered securities offering, even if the token isn’t a security today.
Do governance tokens count as securities?
It depends on the details. A governance token used purely to vote on protocol changes, with no profit-sharing or dividend rights, leans toward utility. But if the token also entitles holders to a share of platform revenue, or if it was marketed with promises of price appreciation, it can look a lot more like a security. There’s no blanket answer; each governance token needs to be assessed on its own facts.
What’s the difference between a token and a coin?
A coin (like Bitcoin or Litecoin) runs on its own independent blockchain and typically works as a form of currency. A token is built on top of an existing blockchain, like Ethereum, using that network’s infrastructure and can represent almost anything: access rights, ownership, loyalty points, or collectibles.
If I’m outside the US, do I still need to worry about SEC rules?
Possibly. If you sell tokens to US-based buyers, market to a US audience, or use US infrastructure in certain ways, SEC rules can still apply regardless of where your company is based. Selling exclusively to non-US buyers under an exemption like Regulation S can avoid US securities law, but you’ll then need to comply with the rules of wherever your buyers actually are, such as MiCA in the EU or MAS rules in Singapore.
Aviso : Este artigo tem caráter meramente informativo e não deve ser considerado como aconselhamento de investimento ou negociação. Nada aqui contido deve ser interpretado como aconselhamento financeiro, jurídico ou tributário. Negociar ou investir em criptomoedas acarreta um risco considerável de perda financeira. Sempre realize uma pesquisa completa antes de tomar qualquer decisão de investimento ou negociação.
Negocie com comprovante de reservas.
A UEEx publica auditorias mensais e verificações de terceiros em todos os mercados em que está cotada.
Análises de mercado, estratégias de negociação, insights sobre futuros e alertas de segurança entregues semanalmente. Lido por mais de 10,000 traders de criptomoedas.