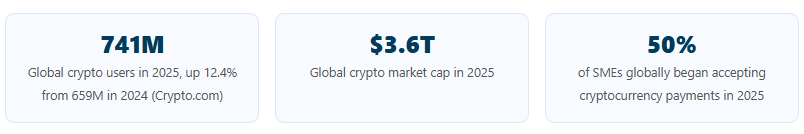
Cryptocurrency is a system of digital money secured by advanced cryptography and recorded on decentralised blockchain networks, with no central bank controlling its supply. It offers a range of benefits traditional finance cannot match: global 24/7 accessibility, transaction costs as low as a fraction of a cent, self-sovereign ownership, and open access to financial services for the 1.4 billion adults worldwide who lack a bank account. Global crypto ownership reached 741 million people in 2025.
Key Takeaways
Global crypto ownership reached 741 million people in 2025, a 12.4% increase year-over-year (Crypto.com), projected to approach 1 billion by 2026.
Blockchain cross-border payments cost 0.5 to 1% versus 2 to 7% for traditional bank transfers, with settlement in minutes rather than 3 to 5 business days.
Transferring $10,000 in Bitcoin costs approximately $3 in fees. The same transfer through a traditional bank can cost $300 or more when accounting for wire fees, FX markups, and intermediary charges.
Approximately 1.4 billion adults worldwide remain unbanked. Crypto and DeFi provide financial services to anyone with a smartphone and internet connection, regardless of location, credit history, or government ID.
The stablecoin market surpassed $305 billion in total supply in 2025 and settled over $32 trillion in transaction volume, demonstrating crypto’s transition from speculative asset to payment infrastructure.
The DeFi market offered lending, borrowing, and yield-bearing savings products with a total value locked of approximately $98.4 billion in 2025, accessible without a bank account or credit check.
Cryptocurrency is much bigger than just Bitcoin. Think of it as a system rather than a single currency: a new way of handling digital money, secured by advanced cryptography and decentralised networks. Unlike traditional currencies controlled by central banks, cryptocurrencies rely on a distributed ledger called blockchain technology to ensure secure, transparent, and tamper-proof transactions. No single government, bank, or institution controls the flow of crypto.
Beyond Bitcoin, the ecosystem includes Ethereum, a platform for building applications using smart contracts that automatically execute transactions when certain conditions are met; Ripple (XRP), focused on making international transactions faster and cheaper; stablecoins like USDC and USDT that maintain a 1:1 peg to the US dollar; and thousands of other specialised tokens serving specific purposes in finance, gaming, supply chain, and beyond.
Join UEEx
Experience the World’s Leading Digital Wealth Management Platform
Benefits 1 to 5: Cost, Speed, Access, Inclusion, and Control
1. Lower Transaction Costs: One of the most tangible benefits of cryptocurrency is dramatically lower transaction fees compared to traditional financial services. Traditional wire transfers for a $10,000 payment typically include a $40 wire fee, a 3% FX markup ($300), and an additional $25 intermediary fee, meaning the recipient may receive only $9,635. The same transfer via Bitcoin costs approximately $3 in total fees. Stablecoin cross-border payments on networks like Solana cost less than $0.01. Credit card fees typically range from 2 to 3% of the transaction value. Blockchain payments cost 0.5 to 1%. These savings compound substantially for businesses making frequent international payments: one reported case study showed switching to RippleNet reduced payment costs by approximately $187,000 annually on $1.2 million in transactions.
2. Faster Transaction Settlement: Traditional international wire transfers through the SWIFT network take 3 to 5 business days, and same-day credit is not guaranteed. Blockchain transactions settle in minutes, with many modern networks completing transfers in seconds. XRP transactions settle in 3 to 5 seconds. Solana finalises blocks in approximately 400 milliseconds. Even Bitcoin, the slowest major blockchain, confirms transactions in 10 to 20 minutes on average. This speed operates 24 hours a day, 7 days a week, 365 days a year: no banking hours, no weekends, no public holiday delays. For businesses managing global supply chains and cash flows, faster settlement directly improves financial operations.
3. Global Accessibility Without Geographic Restrictions: Cryptocurrency operates on a global network. Anyone with a smartphone and internet connection can send or receive crypto, regardless of where they live, what currency their country uses, or what restrictions their government places on capital flows. This accessibility makes crypto particularly attractive in regions with limited banking infrastructure, high fees associated with traditional financial services, capital controls, or unstable national currencies. Vietnam leads global per-capita crypto adoption with 27% ownership. Nigeria’s crypto usage hit 41% of adults in 2025. In Lebanon, approximately 19.8% of citizens use crypto wallets as their primary store of value following banking crises that froze conventional accounts.
4. Financial Inclusion for the Unbanked: Approximately 1.4 billion adults worldwide remain unbanked, unable to access basic financial services like savings accounts, loans, or payment systems. Cryptocurrency bypasses the traditional requirements for financial access: no physical bank branch visit, no minimum deposit, no credit history, no government-issued ID required to create a wallet and transact. In Southeast Asia, 70% of adults are unbanked or underbanked, and crypto adoption is driven precisely by this need. In Africa, 84% of crypto transactions are mobile-based, showing how smartphone-first crypto adoption is serving as the banking infrastructure these populations never had. In 2025, approximately 15% of unbanked individuals globally were using cryptocurrency for transfers, and this proportion is growing.
5. User Control and Financial Sovereignty: In traditional banking, your money is not truly under your sole control. A bank can freeze your account, place limits on withdrawals, block international transfers, or go bankrupt. With cryptocurrency, your funds are controlled by your private key, a unique cryptographic code known only to you. No government, bank, or third party can access, freeze, or seize funds in a self-custodied crypto wallet without that key. This financial sovereignty is not merely theoretical: during the 2022 Canadian trucker protests, the government froze bank accounts of protesters. During banking crises in countries like Lebanon, Cyprus, and Argentina, citizens with crypto holdings could access their funds when conventional bank accounts were frozen or limited. Ukraine received over $2.1 billion in crypto-aided assistance and funding for defence during the conflict, demonstrating how crypto moves where traditional financial infrastructure cannot reach.
“Crypto adoption is truly global. Emerging markets where remittances, dollar access via stablecoins, and mobile-first finance continue to accelerate adoption are driving growth at the same time as mature institutional markets.”
Benefits 6 to 10: Security, Transparency, Inflation Protection, DeFi, and Returns
6. Enhanced Security Through Decentralization: Blockchain’s decentralised architecture makes it extraordinarily resistant to the type of large-scale data breaches that regularly hit centralised financial institutions. Every transaction is secured by cryptographic hashing and distributed across thousands of nodes simultaneously. To alter any historical transaction, an attacker would need to re-mine every subsequent block and gain consensus from the majority of the network, a practically impossible task. While centralised exchanges can be hacked and individual users can lose funds through poor security practices, the underlying blockchain protocol itself has never been successfully compromised for Bitcoin or Ethereum. This is a fundamentally different security model from centralised banking, where a successful database breach can expose millions of accounts at once.
7. Transparency and Auditability: Every transaction on a public blockchain is recorded permanently and is visible to anyone. This creates an unprecedented level of financial transparency. Every payment is timestamped, the sending and receiving addresses are visible, and the transaction amount is permanently on the public record. This transparency has real practical value: charitable organisations can demonstrate exactly how donations are used; businesses can provide auditable payment records without relying on third-party verification; and governments can monitor public spending on blockchain with full accountability. Privacy-focused users can also use privacy coins or transaction mixing techniques to maintain confidentiality while retaining the blockchain’s security benefits.
8. Potential Protection Against Inflation: Traditional fiat currencies lose purchasing power over time through inflation, driven by central bank monetary expansion. Bitcoin’s supply is mathematically capped at 21 million coins, with approximately 94% already mined as of 2025, making it provably scarce in a way no fiat currency can be. Governments cannot print more Bitcoin. This scarcity has led many investors, particularly in countries experiencing severe inflation, to hold Bitcoin as a store of value analogous to digital gold. In Nigeria, over 35% of crypto remittance recipients held their crypto for six months or longer as a direct inflation hedge. In countries like Zimbabwe, where crypto transactions represent an estimated 6% of GDP, and Pakistan, where 18.7% of crypto remittances substitute for a depreciating rupee, Bitcoin and stablecoins serve as practical inflation protection for everyday citizens.
9. Access to Decentralised Finance (DeFi): Decentralized Finance is one of the most transformative benefits of the crypto ecosystem. DeFi applications built on blockchains like Ethereum offer lending, borrowing, yield-bearing savings, insurance, trading, and derivatives, all without requiring a bank account, a credit check, a minimum deposit, or a government ID. The DeFi market had a total value locked of approximately $98.4 billion in 2025. A DeFi lending protocol does not care about your credit score or what country you live in; it assesses the collateral you provide. For the 1.4 billion unbanked people globally, DeFi represents access to financial tools that traditional banking has denied them. For experienced investors, DeFi protocols have historically offered significantly higher yields than traditional savings accounts.
10. Historically Strong Investment Returns: Bitcoin was the best-performing major asset class in 8 out of 11 years from 2014 to 2024, averaging a 54% annualised return over that period according to BlackRock. Bitcoin reached an all-time high of $126,200 in October 2025. An investor who placed $1 in Bitcoin in 2015 at approximately $300 would have seen that grow to over $300 at December 2025 prices, a 30,000%+ gain. These returns come with significant volatility and frequent sharp drawdowns, but for long-term investors who maintained their positions, the rewards have been extraordinary. The approval of spot Bitcoin ETFs in January 2024 opened these returns to mainstream investors through regulated, familiar investment vehicles: BlackRock’s IBIT surpassed $50 billion in AUM in under a year.
Join UEEx
Experience the World’s Leading Digital Wealth Management Platform
Benefits 11 to 15: Privacy, Programmability, 24/7 Markets, No Chargebacks, and Asset Ownership
11. Pseudonymity and Financial Privacy: Cryptocurrency transactions link to wallet addresses rather than verified real-world identities, providing a degree of pseudonymity that traditional banking cannot offer. While major centralized exchanges now require KYC (Know Your Customer) verification to comply with anti-money laundering regulations, on-chain transfers between self-custodied wallets are not inherently tied to personal identity. This is valuable for individuals in authoritarian environments, users who wish to keep their financial activity private from corporations that sell data, and anyone who simply values financial privacy as a fundamental right. Privacy-preserving coins like Monero and Zcash offer enhanced anonymity features for those who require them.
12. Programmable Money via Smart Contracts: Cryptocurrency, particularly on smart contract platforms like Ethereum, enables programmable money: digital funds that automatically execute according to pre-written code when specified conditions are met, with no need for manual intervention or a trusted intermediary. Smart contracts power decentralised exchanges, automated lending, yield farming, insurance payouts, cross-border escrow, payroll automation, and supply chain payments. In healthcare, education, and legal services, smart contracts are being deployed to automate processes that previously required lawyers, notaries, and manual paperwork. The programmability of crypto is not merely a feature: it is an entirely new capability that makes money behave like software.
13. Markets Open 24 Hours a Day, 7 Days a Week: Traditional stock markets open at 9:30 AM and close at 4:00 PM Eastern Time, five days a week. Banks have business hours, public holidays, and maintenance windows. Cryptocurrency markets never close. Bitcoin can be bought, sold, or transferred at 3:00 AM on Christmas Day just as easily as at noon on a Tuesday. This round-the-clock availability benefits international traders dealing across time zones, investors who want to respond immediately to global news, and individuals in regions where their local banking infrastructure has limited operating hours. The 24/7 nature of crypto also means that price discovery is continuous and global, incorporating information from every corner of the world in real time.
14. Elimination of Chargebacks for Merchants: One of the most significant financial costs for merchants accepting credit cards is chargebacks: disputed transactions that result in forceful reversal of payment, often due to fraud. Credit card chargebacks cost merchants globally billions of dollars annually in lost revenue, processing fees, and administrative costs. Cryptocurrency transactions are irreversible by design once confirmed on the blockchain. A completed crypto payment cannot be disputed and reversed by the payer. For merchants, this eliminates chargeback fraud entirely and reduces payment processing costs significantly. This is one reason why 50% of SMEs globally began accepting cryptocurrency payments in 2025, with adoption growing 45% year-on-year.
15. True Digital Asset Ownership: When you hold funds in a traditional bank account, you are an unsecured creditor of that bank. The bank legally owns your deposits and owes them to you. If the bank fails, you are in the queue of creditors. With cryptocurrency held in a self-custodied wallet, you directly own the digital asset. There is no counterparty to default on you. Non-Fungible Tokens (NFTs) extend this concept to digital art, music, gaming items, and collectibles, enabling provable, transferable ownership of digital content that previously could be infinitely copied. True digital ownership is a new property right that did not exist before blockchain technology.
Benefits 16 to 20: Cross-Border Commerce, Remittances, Innovation, Portfolio Diversification, and Censorship Resistance
16. Enabling Cross-Border Commerce for Small Businesses: Traditional international payment systems create meaningful barriers for small businesses that want to serve customers or pay suppliers globally. Currency conversion fees, wire transfer minimums, rejected transactions from unsupported countries, and multi-day settlement delays all add friction that disproportionately harms small operators. Cryptocurrency enables a business in Nigeria to pay a supplier in Japan instantly, with predictable costs, without needing accounts in both countries or paying correspondent bank markups. The payment adoption growth of 45% in 2025, combined with 50% of SMEs globally accepting crypto, reflects how businesses are using crypto to reach customers and suppliers that traditional payment rails exclude.
17. Revolutionising International Remittances: Remittances are a critical financial lifeline: global remittance flows exceeded $800 billion in 2024, much of it sent by migrant workers to family in developing countries. Traditional remittance channels like Western Union charge average fees of approximately 6.4% per $200 transfer, according to World Bank data. Crypto-based remittances charge a fraction of that: in the Philippines, stablecoin remittances have reduced fees from approximately 6% to nearly 1% while speeding transfers from days to minutes. Crypto remittances are estimated at approximately $25 billion annually in 2025, growing rapidly. In 2025, approximately 15% of unbanked individuals globally used cryptocurrency for transfers. India alone has approximately 25 million rural users relying on mobile-based crypto wallets for remittances.
18. A Platform for Continuous Financial Innovation: The cryptocurrency ecosystem is one of the most rapidly innovating areas in technology and finance. The underlying blockchain protocol enables applications that would be impossible in traditional finance: decentralised autonomous organisations (DAOs) that govern themselves by vote without any management layer; play-to-earn games where players earn real income from in-game activity (blockchain gaming adoption grew 30% in 2025); yield-generating NFTs; tokenised real-world assets including property and securities; automated market makers that provide liquidity 24/7 without human intervention; and Layer-2 scaling solutions that process thousands of transactions per second at near-zero cost. This innovation layer compounds over time, creating new financial instruments and services faster than any centralised institution.
19. Portfolio Diversification With Low Long-Term Correlation: Institutional investors and financial advisors increasingly view a modest cryptocurrency allocation as a portfolio diversification tool rather than pure speculation. Bitcoin’s historically low long-term correlation with stocks and bonds means that at modest allocation sizes (3 to 5% of portfolio), crypto can actually reduce overall portfolio volatility while providing access to an asset class with a different return driver. BlackRock’s research notes that a Bitcoin allocation may have a smaller impact on portfolio volatility than similar-sized positions in certain individual stocks. With 59% of institutional investors increasing their crypto allocations above 5% of AUM in 2025, and Bitcoin included in multiple public pension fund portfolios, institutional endorsement of crypto’s portfolio role continues to grow.
20. Censorship Resistance and Protection from Financial Exclusion: Perhaps the most philosophically significant benefit of decentralized cryptocurrency is its resistance to censorship. No government, corporation, or individual can prevent a Bitcoin transaction between two willing parties who control their own wallets. No payment processor can choose not to serve a particular political view or commercial category. No bank can decide which businesses or individuals deserve access to the financial system. This property has practical humanitarian value: during the Russian invasion of Ukraine, $2.1 billion in crypto-aided assistance and defence funding reached the country directly without needing access to the global banking system. During political crises in Belarus, Cuba, and Myanmar, activists received international funding through crypto when traditional financial channels were blocked by their governments.
2 to 7% (wire fees + FX markup + intermediary charges)
Settlement time
Seconds to minutes; 24/7/365
1 to 5 business days; banking hours only
Account requirements
Smartphone and internet access only
Government ID, address proof, minimum deposit, credit check (varies)
Control over funds
Complete; private key = sole ownership (self-custody)
Bank holds funds; can freeze, limit, or confiscate
Transaction reversibility
Irreversible once confirmed (eliminates chargebacks)
Reversible; chargebacks possible (fraud risk for merchants)
Savings yield
DeFi: 3 to 15%+ APY (varies; higher risk)
Savings accounts: 0.01 to 5% APY (FDIC insured)
Privacy
Pseudonymous (public blockchain); optional full privacy (privacy coins)
Full identity linkage; data shared with government and third parties
Regulatory protection
Improving; no deposit insurance for self-custody
Strong; FDIC insures deposits up to $250,000 in US
What Are the Limitations of Cryptocurrency?
A balanced assessment of crypto’s benefits requires acknowledging the limitations that still exist and are important for any new user to understand:
Price volatility: Most cryptocurrencies except stablecoins are subject to significant price swings. Bitcoin experienced a 36% correction in late 2025. Volatility is manageable through position sizing, dollar-cost averaging, and long-term holding, but it is real.
Irreversibility: A confirmed blockchain transaction cannot be reversed. Sending crypto to the wrong address or losing your private key typically means permanent loss of funds with no recourse. This places full responsibility on the user.
Regulatory uncertainty: The regulatory environment for crypto continues to evolve. While it improved substantially in 2025 with the GENIUS Act and MiCA, regulatory changes in major economies can affect market access and asset values.
Technical learning curve: Properly understanding wallets, private keys, seed phrases, gas fees, and network selection requires more technical knowledge than opening a bank account. User-friendly apps have lowered this barrier significantly, but it remains real for many potential users.
Security risks at the user level: While the blockchain itself is secure, users are responsible for their own key management. Phishing attacks, malware, SIM-swapping, and social engineering are real threats. Using a hardware wallet, keeping private keys offline, and enabling 2FA on all exchanges are essential practices.
Limited consumer protections: Unlike bank accounts, most crypto holdings have no deposit insurance. If a centralised exchange is hacked or becomes insolvent, users may lose funds. This reinforces the value of self-custody for significant holdings.
Getting started safely: The most important first step for any new crypto user is choosing a reputable exchange with strong security practices and keeping only trading funds on exchanges. Long-term holdings should be in a hardware wallet where you control the private key. Never share your seed phrase with anyone or enter it on any website. Start small, learn the technology, and scale your exposure as your understanding grows.
1.4 billion unbanked; crypto accessible with a smartphone
Unbanked populations in developing markets; migrant workers
Inflation protection
Bitcoin capped at 21M; 94% already mined in 2025
Savers in high-inflation economies; long-term investors
DeFi yield access
$98.4B total value locked in DeFi in 2025
Investors seeking yield above bank rates; unbanked needing loans
Investment returns
54% avg annual Bitcoin return 2014 to 2024 (BlackRock)
Long-term investors who can tolerate volatility and drawdowns
Censorship resistance
$2.1B in crypto-aided assistance reached Ukraine in conflict
Activists, journalists, politically exposed persons, citizens in authoritarian states
Frequently Asked Questions
What are the main benefits of using cryptocurrency?
The main benefits include lower transaction costs compared to traditional banking (blockchain payments cost 0.5 to 1% versus 2 to 7% for traditional cross-border transfers); faster settlement in minutes versus 3 to 5 business days; financial inclusion for the approximately 1.4 billion unbanked adults globally; user control over funds without reliance on banks; transparency through publicly verifiable blockchain records; access to DeFi yield and financial services; inflation protection through fixed-supply assets like Bitcoin; and 24/7 global accessibility with no banking hours or geographic restrictions.
How many people use cryptocurrency globally in 2025?
Global cryptocurrency ownership reached approximately 741 million people in 2025 according to Crypto.com’s 2025 Market Sizing Report, a 12.4% increase from 659 million in 2024. The global user base is projected to approach 1 billion by 2026. Asia-Pacific leads with approximately 43% of global crypto users. India leads by individual country user base with approximately 150 million users, followed by the US and Nigeria. Statista projects that by the end of 2025 the number could reach approximately 861 million users globally.
Is cryptocurrency safe to use?
Cryptocurrency offers a different security model from traditional banking. The blockchain ledger itself is extremely difficult to tamper with due to its decentralised, cryptographically linked structure. Your primary security responsibility is protecting your private key. Crypto funds in a self-custodied wallet cannot be seized or accessed without it. However, centralised exchanges can be hacked, and lost private keys mean lost access with no recovery. Using a reputable hardware wallet for significant holdings, enabling 2FA, and storing backup seed phrases securely offline are the most important security practices.
Can cryptocurrency replace traditional banking?
Cryptocurrency is unlikely to fully replace traditional banking in the near term, but it is complementing and disrupting it significantly. DeFi platforms now offer lending, borrowing, yield on savings, and trading without any bank account requirement. The stablecoin market surpassed $305 billion in 2025, settling over $32 trillion in transaction volume. For the approximately 1.4 billion unbanked adults globally, crypto and DeFi may become the primary financial access layer, essentially replacing banking rather than just complementing it for that population.
What is the best cryptocurrency for everyday payments in 2026?
The best cryptocurrencies for everyday payments in 2026 depend on use case. For stable value, stablecoins like USDC and USDT offer dollar parity with minimal fees. XRP settles in 3 to 5 seconds at approximately $0.001 per transaction, making it ideal for remittances. Solana and Polygon offer fees under $0.01 with high throughput. Bitcoin via the Lightning Network enables near-instant sub-cent micropayments. For most everyday uses, a stablecoin on a fast Layer-1 or Layer-2 network provides the best combination of fee efficiency, speed, and price stability.
Join UEEx
Experience the World’s Leading Digital Wealth Management Platform
Orebiyi Eniola is a writer whose soul work is content marketing with a focus on the cryptocurrency industry. Equipped as a marketing storyteller and driven by a passion for crafting impactful stories, she helps businesses connect with their audiences via strategic and thought-provoking writing. Orebiyi assists businesses in projecting their stories and actualizing their ambitions through the force of words. She likes to settle in with her favorite fiction novels when not pounding on her keyboard.
Disclaimer: This article is intended solely for informational purposes and should not be considered trading or investment advice. Nothing herein should be construed as financial, legal, or tax advice. Trading or investing in cryptocurrencies carries a considerable risk of financial loss. Always conduct due diligence before making any trading or investment decisions.
Trade with proof of Reserves
UEEx publish monthly audits and third party verification on every listed market.