Crypto capital gains tax is the tax owed on profits from selling, trading, or otherwise disposing of cryptocurrency – calculated as your sale price minus your original cost basis. The IRS treats digital assets as property under Notice 2014-21, which means nearly every taxable event – swapping Bitcoin for Ethereum, paying for goods with crypto, receiving staking rewards – triggers a reportable gain or loss. As of 2026, the federal rate ranges from 0% to 37% depending on your holding period and income level, and a new reporting framework under Form 1099-DA has made non-compliance far riskier than in prior years.
Join UEEx
Experience the World’s Leading Digital Wealth Management Platform
When you sell an asset for more than you paid for it, the profit is a capital gain. Governments tax this profit to capture a share of wealth created through asset appreciation. The IRS formally classified digital assets as property in Notice 2014-21, and that classification has remained in place through 2026 – meaning every crypto disposal is treated the same way as selling a stock or real estate.
Your taxable gain is calculated as: Sale Price minus Cost Basis = Capital Gain (or Loss). Cost basis is the original amount you paid for the crypto, including any fees paid at the time of purchase. If you received crypto as income – through staking rewards, airdrops, or payment for services – the fair market value at the time of receipt becomes your cost basis for future sales. Understanding this single formula is the foundation of every crypto tax calculation you will ever make.
Which Crypto Events Trigger a Taxable Gain?
Not every interaction with cryptocurrency creates a tax liability. The distinction matters because many investors assume they only owe tax when they cash out to dollars – an assumption that leads to significant under-reporting.
Which Crypto Actions Are Taxable?
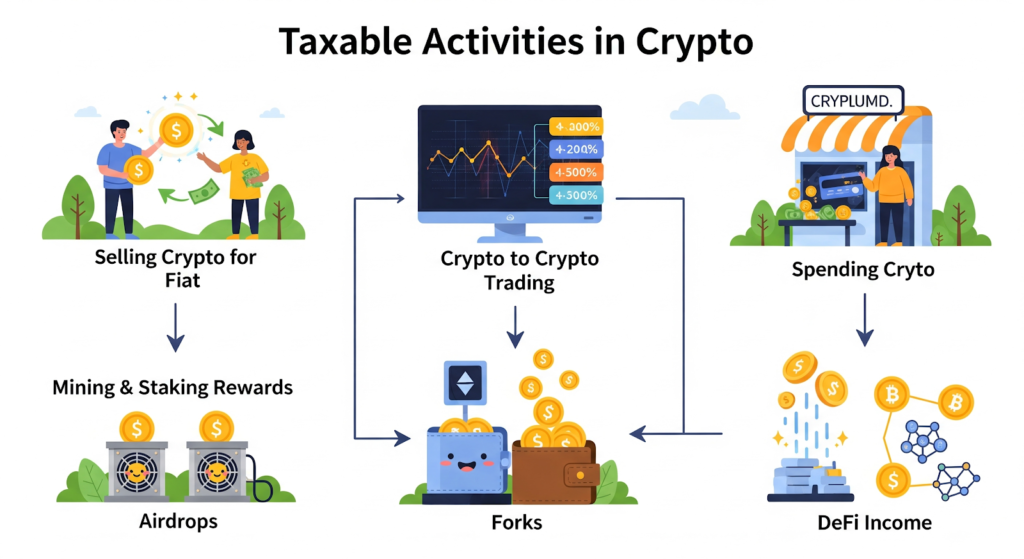
Selling cryptocurrency for fiat currency (USD, EUR, etc.)
Trading one cryptocurrency directly for another (e.g., ETH for SOL) – the IRS treats this as a disposal of the first asset
Using cryptocurrency to buy goods or services
Receiving staking and yield-farming rewards (taxed as ordinary income at receipt; subject to capital gains on later sale)
Receiving airdrops and hard fork coins (taxed as ordinary income at fair market value on receipt)
Getting paid in crypto for employment or freelance work
Swapping tokens on a DEX like Uniswap – the IRS treats on-chain swaps identically to centralized exchange trades
The single most impactful decision a crypto investor can make for their tax bill is timing. The IRS applies two entirely different rate schedules depending on whether you held an asset for more or less than one year.
Holding Period
Tax Category
2026 Federal Rate Range
Example: $10,000 Gain
Under 12 months
Short-term capital gain
10% – 37% (ordinary income rates)
$2,200 – $3,700 tax owed
Over 12 months
Long-term capital gain
0%, 15%, or 20%
$0 – $2,000 tax owed
Any period – staking/mining income
Ordinary income
10% – 37%
$1,000 – $3,700 tax owed
What Are the 2026 Long-Term Capital Gains Brackets?
As of 2026, the IRS applies the following long-term capital gains rates for individual filers:
0% rate: Taxable income up to $48,350 (single filers) or $96,700 (married filing jointly)
15% rate: Taxable income from $48,351 to $533,400 (single) or $96,701 to $600,050 (married filing jointly)
20% rate: Taxable income above $533,400 (single) or $600,050 (married filing jointly)
A single filer with modest total income can sell long-held crypto at a 0% federal rate – a legitimate planning opportunity worth building around every year.
Join UEEx
Experience the World’s Leading Digital Wealth Management Platform
In Q1 2026, one of the most significant structural changes to US crypto taxation took effect. The IRS introduced Form 1099-DA (Digital Asset Proceeds from Broker Transactions), requiring custodial brokers – exchanges like Coinbase, Kraken, and Gemini – to report gross proceeds from customer transactions directly to the IRS, beginning with transactions on or after January 1, 2026.
How Does Form 1099-DA Change Reporting?
For the 2026 tax year (with forms issued in early 2026), brokers must report gross proceeds. Cost basis reporting does not become mandatory until transactions in 2026, meaning the first 1099-DA that includes gain/loss data will arrive in early 2027. This phased rollout creates a gap: the IRS will receive your gross sales figures, but you still need to calculate and document your own cost basis for 2026 returns.
If you used multiple wallets, moved coins between exchanges, or acquired crypto over several years, you need reliable records of every purchase price. The IRS will see what you sold; it will not automatically see what you paid. Discrepancies between your reported gains and the 1099-DA amounts are a likely audit trigger.
One important distinction: decentralized or non-custodial brokers are not subject to 1099-DA reporting requirements under the final IRS regulations. DeFi trades on protocols like Uniswap will not generate a 1099-DA – you are responsible for tracking and reporting those transactions yourself.
How Is Crypto Capital Gains Tax Calculated?
Walking through a concrete calculation shows how the rules apply in practice.
Step-by-Step Calculation Example
Record your cost basis: You bought 1 ETH for $2,000 in January 2024, including a $10 exchange fee. Cost basis = $2,010.
Determine sale proceeds: You sell that ETH in March 2026 for $3,500, minus a $15 fee. Net proceeds = $3,485.
Calculate the gain.$3,485 minus $2,010 = $1,475 capital gain.
Identify the holding period: You held for just over 14 months – this qualifies as a long-term gain.
Apply the rate: If your taxable income falls in the 15% long-term bracket, you owe $221.25 on this gain.
Had you sold in December 2024 – under 12 months from purchase – the same $1,475 gain would be taxed as ordinary income. At a 22% bracket, that is $324.50. Waiting one additional month saves over $100 on a single, modest transaction. On a $50,000 gain, the difference between the 37% short-term rate and the 20% long-term rate is $8,500.
What Are the Most Effective Tax Reduction Strategies?
Tax-Loss Harvesting – and Why 2026 May Be the Last Easy Year
If you hold positions showing a loss, selling them before year-end generates a realized loss that offsets gains from profitable trades. Unlike stocks, cryptocurrency is not currently subject to the wash-sale rule in the US – meaning you can sell at a loss and immediately repurchase the same asset. This remains legal as of 2026, but it is under active legislative scrutiny. A bipartisan bill introduced in December 2026 – the PARITY Act – would apply wash-sale rules to crypto. If passed, the strategy becomes unavailable. Harvest losses while the window is still open.
The One-Year Holding Strategy
Waiting 12 months and one day before selling any position converts a short-term gain (taxed at up to 37%) into a long-term gain (taxed at 0%–20%). For active traders who frequently flip positions, this single discipline is the most powerful legal tax reducer available – no complex planning required.
Timing Sales in Lower-Income Years
Because long-term capital gains rates are income-sensitive, selling during a year when your other income is unusually low – such as the first year of retirement or a year between jobs – can move gains into the 0% bracket entirely. This takes forward planning but produces real, repeating savings.
Using a Crypto IRA
Self-directed Individual Retirement Accounts allow cryptocurrency investments. Gains inside a Traditional IRA are tax-deferred until withdrawal; gains inside a Roth IRA are tax-free entirely, provided you meet holding and age requirements. As of 2026, custodians including Alto IRA and Bitcoin IRA offer broad crypto access within these structures. The IRS has not restricted crypto within retirement accounts, though the regulatory environment bears watching.
Charitable Donation of Appreciated Crypto
Donating long-held crypto directly to a qualified charity avoids capital gains tax on the appreciation entirely and gives you a deduction for the full fair market value at the time of donation. You avoid the tax; the charity receives the full asset value. This works well for coins with very large unrealized gains that would otherwise face the 20% rate plus potential Net Investment Income Tax.
How Does Crypto Tax Work Outside the United States?
Tax treatment varies widely across jurisdictions. A few reference points as of 2026:
United Kingdom: HMRC treats crypto as a capital asset. The annual Capital Gains Tax allowance dropped from £12,300 to £3,000 in 2024, significantly increasing tax exposure for active traders.
European Union: Treatment differs by member state, but the EU’s Markets in Crypto-Assets (MiCA) regulation, which phased in fully in 2026, is driving harmonization of exchange reporting requirements across all 27 members.
Germany: Crypto held for more than one year is tax-free regardless of profit amount – one of the most favorable regimes among developed economies.
Portugal: Reversed its previously zero-tax policy in 2023 and now applies a 28% rate to short-term crypto gains.
Global reporting: The IRS participates in FATCA and the OECD’s Crypto-Asset Reporting Framework (CARF), which enables international exchange of taxpayer data. Using foreign exchanges does not shield transactions from domestic tax authorities.
With Form 1099-DA now active and the IRS receiving direct transaction data from major US exchanges, non-reporting carries far more risk in 2026 than in prior years. Consequences for deliberate non-compliance include:
Accuracy-related penalties of 20% of the underpaid tax
Fraud penalties up to 75% of the underpaid amount in severe cases
Interest charges on unpaid tax, accruing from the original due date
Criminal prosecution for willful tax evasion, carrying potential prison sentences
The IRS has allocated significantly more enforcement resources to digital assets following the Infrastructure Investment and Jobs Act of 2021, which expanded the definition of “broker” in the tax code to include crypto exchanges. The combination of mandatory reporting and increased enforcement staffing means the era of under-reporting without consequence is over.
Frequently Asked Questions About Crypto Capital Gains Tax
Do I owe tax if I trade one cryptocurrency for another without converting to dollars?
Yes. The IRS treats a crypto-to-crypto trade as a disposal of the first asset and an acquisition of the second at its fair market value. You calculate a gain or loss based on the fair market value of the coin you gave up at the moment of the trade, minus your original cost basis. No dollars changing hands does not affect the taxable outcome. This applies equally to centralized exchange swaps and on-chain DEX trades.
What happens if my crypto loses value and I sell at a loss?
A realized capital loss offsets capital gains dollar-for-dollar. If your losses exceed your gains in a given year, you can deduct up to $3,000 of the remaining net loss against ordinary income ($1,500 if married filing separately). Any loss beyond $3,000 carries forward to future tax years, continuing to offset gains or income until fully used. Losses are one of the few genuinely flexible tools available to crypto investors for managing tax liability.
Are staking rewards taxed differently from selling gains?
Yes, and the distinction has two stages. Staking rewards are treated as ordinary income the moment you receive them, taxed at your marginal rate (10%–37%). Those rewards then become a new asset with a cost basis equal to their fair market value at receipt. When you later sell the staked rewards, any additional appreciation is subject to capital gains tax – short-term or long-term depending on how long you held them after receipt. You may owe two separate taxes on the same tokens at two different times.
How does Form 1099-DA affect my 2026 tax filing?
Starting with the 2026 tax year, custodial exchanges must report your gross proceeds to the IRS on Form 1099-DA. Cost basis information is not yet required for 2026, so you still need your own records to calculate net gains. The IRS will see your total sales; if your reported gains appear significantly lower than those sales figures, it may flag your return for review. DeFi transactions on non-custodial platforms will not generate a 1099-DA – you must track and report those yourself.
Is there a minimum crypto gain that is tax-free?
There is no de minimis exemption for crypto transactions in the US as of 2026. Even a $5 gain on a coffee purchase paid in Bitcoin is technically taxable and reportable. Practically, many small transactions go unreported, but the legal obligation exists for all gains. Legislators have proposed a de minimis rule for transactions under $200 – the PARITY Act introduced in December 2026 includes such a provision – but it had not passed into law as of this writing.
Can crypto tax software handle all of this automatically?
Yes, within limits. Platforms like Koinly, TaxBit, CoinTracker, and TokenTax connect to exchanges via API or CSV import, calculate gains using your preferred accounting method (FIFO, LIFO, or specific identification), and generate IRS-ready forms including Schedule D and Form 8949. As of 2026, TaxBit has a formal data-sharing partnership with several major US exchanges, simplifying reconciliation. These tools handle centralized exchange activity well; DeFi and cross-chain transactions still require manual review for accuracy.
Practical Tips for Managing Your Crypto Tax Liability
Track every transaction from day one.Retroactively reconstructing cost basis across years of trades and multiple wallets is painful and error-prone. Start with a crypto tax platform the moment you make your first purchase – not after you have 300 transactions to reconcile.
Hold beyond 12 months wherever the trade thesis supports it.The difference between 37% and 20% on a $50,000 gain is $8,500. A calendar reminder costs nothing.
Harvest losses before December 31.Review your portfolio in November for positions showing unrealized losses that could offset your 2026 gains before the tax year closes. Act while the wash-sale exemption for crypto still applies.
Document DeFi and staking income carefully.These transactions often generate no automatic record and will not appear on a 1099-DA. Screenshot reward amounts and dates, or use a platform that tracks on-chain activity automatically.
Check your state’s rules separately.States like California apply their own capital gains taxes with no preferential long-term rate. Your federal bill and your state bill can be very different numbers on the same gain.
Do not assume foreign exchanges mean foreign rules.If you are a US person, your worldwide income is taxable regardless of where the exchange is located or what currency is involved. CARF information sharing makes foreign accounts increasingly visible to the IRS.
Get professional advice if you are an active trader.If you execute more than 100 transactions per year or have significant DeFi activity, a CPA who specializes in digital assets will typically save more than their fee – especially as the 1099-DA era increases the chance of IRS scrutiny on mismatched figures.
Hello, welcome to my Profile. I am a passionate content writer, copywriter and fiction writer. I have a zeal to always deliver engaging and high quality content. I’ve perfected the art of blending imaginative thoughts with relatable themes crafting stories that captivates and connects with various audiences.
Disclaimer: This article is intended solely for informational purposes and should not be considered trading or investment advice. Nothing herein should be construed as financial, legal, or tax advice. Trading or investing in cryptocurrencies carries a considerable risk of financial loss. Always conduct due diligence before making any trading or investment decisions.
Trade with proof of Reserves
UEEx publish monthly audits and third party verification on every listed market.