BitGo CEO Mike Belshe has warned that the failure of the U.S. Senate to advance the Clarity Act has left American capital markets exposed to risks created by the growing concentration of exchange, brokerage and custody services witBitGo CEO Says CLARITY Failure Left Capital Markets Exposed
BitGo CEO Mike Belshe has warned that the failure of the U.S. Senate to advance the CLARITY Act has left American capital markets exposed to risks created by the growing concentration of exchange, brokerage and custody services within single digital asset firms.
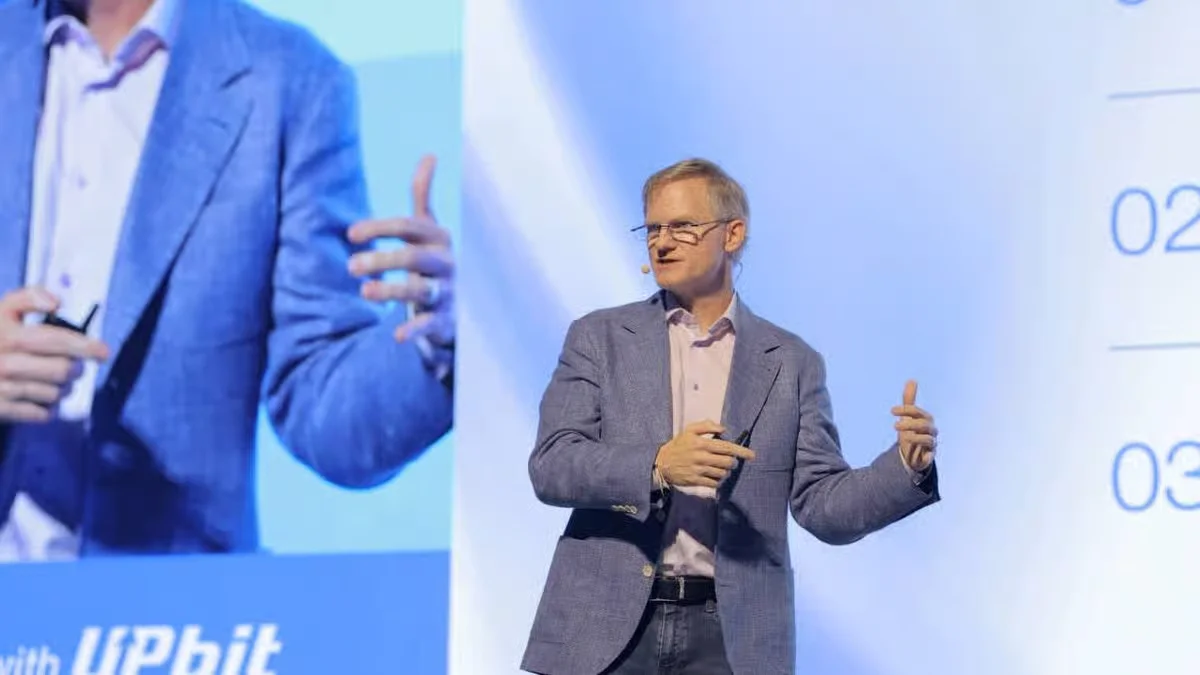
Speaking in an interview with The Block at Korea Blockchain Week 2026, Belshe argued that the absence of a defined market structure could allow companies to become one-stop shops for digital asset trading and custody without sufficient safeguards around those functions.
The Senate’s September 15 procedural vote failed 49–50, falling short of the 60 votes required to advance the legislation. The bill was designed to establish a comprehensive federal framework for digital assets, but negotiations had stalled over several issues, including stablecoin rewards and concerns raised by Democrats about President Donald Trump’s crypto interests.
Key takeaways
- Mike Belshe says combining exchange, brokerage and custody functions could create major concentration risks.
- He identified custody failures and counterparty credit exposure as two key vulnerabilities.
- Belshe compared the potential consequences of a major consolidated platform failure with the 2008 Lehman Brothers collapse.
- The CLARITY Act failed to advance in the Senate in a 49–50 procedural vote on September 15.
- The SEC and CFTC continue developing crypto measures under their existing authority; proposals should be distinguished from rules or exemptions already issued.
Combining financial services concentrates risk
Belshe pointed to the increasing ability of major digital asset companies to operate across several parts of the financial system. He cited Coinbase’s recent addition of a derivatives clearing organization license to its existing exchange and futures commission merchant operations as an example of the broader trend.
According to Belshe, combining these functions creates two major categories of risk. The first is crypto custody risk. Certain crypto assets present a different custody challenge from traditional securities because access is controlled through private keys. If the necessary keys and recovery arrangements are lost or compromised, assets may become inaccessible or be stolen.
The second is counterparty credit risk. When trading, brokerage and custody activities are concentrated inside one institution, problems within that institution could potentially affect several parts of the market simultaneously.
Belshe argued that traditional financial market structures developed safeguards around these risks, while the digital asset sector is increasingly building large integrated platforms without an equivalent comprehensive statutory framework. His concern is about how interconnected services are managed, rather than a claim that crypto firms operate outside all existing regulation.
Belshe draws a comparison with Lehman
Belshe compared the concentration risk to the 2008 collapse of Lehman Brothers, while arguing that a failure involving a major market infrastructure provider could have even broader consequences.
“Imagine if that had been the New York Stock Exchange offering those services and the whole New York Stock Exchange went down.”
His argument was that the financial system survived Lehman’s collapse partly because other institutions and market infrastructure remained operational. A failure involving a dominant venue that simultaneously provided several critical services, he suggested, could transmit disruption across a much larger portion of the market.
Belshe therefore views the absence of clear rules governing the separation or management of these functions as a structural concern rather than simply a compliance issue.
He also said BitGo can continue operating without the CLARITY Act, noting that the company has spent 13 years operating in the digital asset industry. However, he argued that banks and traditional financial institutions may move more cautiously because of concerns about regulatory uncertainty.
Regulators move forward after the Senate setback
The Senate’s failure to advance the legislation has not stopped U.S. regulators from developing crypto measures under their existing authority.
On October 1, the SEC proposed a crypto custody framework for investment advisers and regulated funds. It would permit self-custody in specified circumstances and allow state trust companies to serve as custodians, subject to the proposed requirements.
The proposal concerns client crypto funds and securities held by registered investment advisers, and crypto securities and similar investments held by regulated funds. It remains a proposal, rather than a final rule. The distinction between custodial and non-custodial arrangements remains central to who controls assets and bears responsibility for safeguarding them.
Separately, the SEC issued its Innovation Exemption on September 17, providing temporary, conditional relief for specified tokenized securities trading activities. That measure has a different status and scope from the proposed custody framework.
The CFTC has also continued its crypto policy work. On October 5, it sought public comment through an advance notice of proposed rulemaking concerning crypto asset transactions and markets. This is a preliminary rulemaking step, rather than a completed regulatory framework.
These measures provide direction in the absence of a comprehensive market structure law. However, agency actions must remain within existing statutory authority and can be subject to judicial review or later revision.
Conclusion
Belshe’s warning highlights a central structural question facing the U.S. digital asset market: how should exchange, brokerage and custody functions interact as crypto firms expand across financial services?
His comparison with Lehman is an assessment of the potential consequences of concentrated financial infrastructure, rather than evidence that such a collapse is imminent. The concern is that a failure at a major platform could affect several market activities at once.
Following the September Senate setback, the SEC and CFTC continue developing measures under their existing authority. How those measures address concentration, custody and counterparty risks remains important while Congress considers broader market structure legislation.